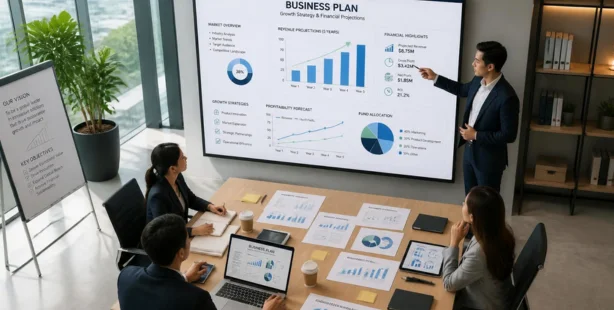
A strong business plan turns an idea into decisions you can test, explain, and fund. Business plans also connect customer demand, operations, marketing, and cash needs before you commit money. The goal is not a polished document for a shelf; it is a useful action plan.
A business plan explains what your company does, who it serves, how it earns money, and where it is going. It connects market research, operations, marketing, and financial projections in one usable document. For U.S. founders, the right format depends on whether the plan supports internal decisions, a loan, or outside investment.
| Key question | Practical answer |
| What is it for? | Clarify the model, guide decisions, support financing, and align partners. |
| Common formats | Traditional plans and lean startup plans. |
| Core content | Company, market, offer, operations, marketing, team, funding needs, and financials. |
| Best starting point | Choose the reader and decision before choosing the format. |
| When to update | Review after major changes and before seeking financing. |
TL;DR
- Start with the decision your plan must support.
- Use a traditional format for detailed financing needs.
- Use a lean format for fast internal planning and testing.
- Build forecasts from evidence, not wishful targets.
- Write the executive summary after the main sections.
- Update the plan when assumptions, costs, customers, or goals change.
Why Business Plans Still Matter
Business plans force you to define your customer, offer, costs, revenue model, and near-term priorities. The U.S. Small Business Administration says a plan can guide management and support conversations with lenders or investors. That makes the planning process useful even without outside funding.
The document also gives you a place to record assumptions before they become expensive commitments. You can compare expected demand with staffing, inventory, equipment, and marketing costs. When results differ from the forecast, you can identify which assumption needs attention.
Traditional vs. Lean: Choose the Right Format
The SBA describes traditional and lean startup formats as two common approaches. Traditional plans are detailed and often suit lenders or investors who need supporting information. Lean plans summarize the main business elements and can work well for early internal planning.
| Format | Best for | Typical depth | Main advantage |
| Traditional | Loans, investors, complex operations | Detailed | Gives readers supporting evidence and financial context |
| Lean startup | Internal planning, simple models, early testing | Concise | Makes assumptions easier to review and revise |
Choose the shortest format that still answers your reader’s questions. A bank may need deeper financial support than a cofounder reviewing an early concept. Your audience should control the depth, not a fixed page count.
What a Strong Business Plan Should Include
Most complete plans cover the same decision areas, even when section names differ. The SBA outline includes executive summary, company description, market analysis, organization, products, marketing, funding needs, and financial projections. An appendix can hold supporting documents that would interrupt the main flow.
Each section should answer a practical question, not fill space. The market section should explain who buys and why, while financials show how the model works numerically. A useful plan connects those sections so the story and numbers support each other.
How to Build Your Plan in 9 Steps
Use this sequence to reduce rework and keep the document tied to evidence. You can adjust the order for your industry, but each step should produce a decision or measurable assumption. Save the executive summary for last, because it should reflect the completed plan.
- Define the purpose and reader. Decide whether the plan supports internal execution, lending, investment, partnerships, or a major expansion.
- Describe the customer problem. State who experiences the problem, how often it occurs, and why existing options fall short.
- Explain your offer. Show what you sell, how customers use it, and why the offer matters.
- Research the market. Estimate demand using credible industry data, customer interviews, competitor evidence, and local information when needed.
- Map competitors and positioning. Compare alternatives on price, convenience, quality, speed, specialization, or another meaningful factor.
- Build the marketing and sales approach. Choose acquisition channels, sales steps, pricing, and retention methods that fit your buyer.
- Plan operations and ownership. Define suppliers, staffing, facilities, technology, responsibilities, and important milestones.
- Build financial projections. Forecast revenue, expenses, cash flow, and funding needs using documented assumptions.
- Write the executive summary last. Condense the opportunity, model, evidence, goals, and financial request into a focused opening section.
Your marketing section should explain how customers will discover and choose the business. Marketeral’s customer-growth guide covers audience research, online presence, social proof, promotions, and partnerships. Those ideas can turn a broad marketing goal into specific acquisition actions.
Build Financial Projections From Evidence
Forecasts are most useful when each number has a traceable reason behind it. The Library of Congress notes several sources for new-business sales estimates. These include industry data, comparable businesses, surveys, and other market information.
Start with a small set of assumptions you can explain in plain language. Estimate customer volume, average revenue per sale, direct costs, fixed expenses, and timing of cash receipts. Then build a conservative base case and test what happens when sales arrive more slowly than expected.
Keep financing requests tied to specific uses of money—Equipment, inventory, hiring, deposits, marketing, and working capital — in both operations and projections. Readers should see how requested funds support measurable milestones.
Turn the Marketing Section Into a Customer Plan
Avoid writing a list of channels without explaining why they fit the target customer. Define who you want to reach, what triggers a purchase, and where buyers look for information. Then connect each channel to a message, budget, conversion goal, and owner.
You should also decide how you will measure customer movement after acquisition. Marketeral’s marketing analytics guide explains how customer data can reveal drop-off points across a customer journey. That thinking can help you set useful sales and retention measures inside the plan.
For many small companies, the first marketing plan can stay simple. Pick a few channels that match buyer behavior, then define monthly activity and expected results. The purpose is a testable system, not a long list of tactics.
Common Mistakes That Make a Plan Less Useful
One common mistake is writing for yourself instead of the person making the next decision. Founders may understand industry shorthand that a lender, partner, or outside investor does not. Clear language makes the underlying model easier to evaluate.
Another mistake is treating forecasts as goals instead of evidence-based estimates. A revenue target does not explain customer volume, pricing, conversion, or capacity. Show the assumptions so a reader can understand how the number was built.
The third mistake is hiding uncertainty. Every new venture has assumptions that may change after launch. Name the biggest risks, define warning signals, and record what you would change first.
A Practical U.S. Example
Imagine a mobile pet-grooming startup serving two suburban counties. The founder estimates demand from pet ownership data, competitor pricing, travel time, van capacity, and customer interviews. Those inputs create a grounded starting point for pricing, route density, staffing, and monthly sales estimates.
The marketing section might focus on local search, veterinarian referrals, neighborhood partnerships, and repeat bookings. Operations would cover vehicle costs, insurance, scheduling, supplies, and service capacity. The financial model would connect appointments per day with revenue, labor, fuel, maintenance, and cash needs.
This example shows why a shorter document can still be rigorous. It does not need decorative pages to be useful. It needs assumptions that connect customer demand, operations, marketing, and money.
Special Cases: Nonprofits, Expansions, and Internal Planning
Not every organization needs the same structure. A nonprofit may emphasize mission, governance, fundraising, compliance, and stakeholder outcomes. Marketeral’s nonprofit startup resource offers related planning considerations for organizations building that foundation.
An expansion plan should focus on the new decision rather than repeat every known company detail. Existing businesses can use historical sales, margins, retention, and operating data to support the case. Internal plans can be shorter when the audience already understands the company.
Whatever the case, keep the document tied to a specific decision. A lender-focused version should make repayment capacity and funding use easy to follow. An internal version should make priorities, owners, milestones, and assumptions easy to review.
Put the Plan to Work
Planning adds value through clearer decisions, stronger assumptions, and faster course corrections. Build the first version around the next decision your business must make. Then use real results to improve the plan as the company develops.
Connect the document to measurable actions, owners, budgets, and review dates. Revisit the customer assumptions when acquisition or retention changes. That turns planning into a management habit instead of a one-time writing exercise.
Frequently Asked Questions
Do business plans need to be long?
No fixed length works for every purpose. A lean document can be brief, while financing may require detailed market and financial support. Include enough evidence to answer the reader’s decision questions without adding filler.
What is the most important section of a business plan?
The answer depends on the reader, but the sections must support each other. Lenders may focus on cash flow, while partners may focus on operations and growth. A strong executive summary helps readers understand how the pieces connect.
Should I write the executive summary first?
It is usually easier to write it after the main sections are complete. By then, you’ll know the strongest evidence, financial needs, and milestones. Place the summary first in the final document, even if you draft it last.
What financial statements should a startup include?
A startup commonly benefits from revenue assumptions, expense projections, cash flow, and a break-even view. Financing discussions may require more detailed statements and supporting schedules. Match the level of detail to the reader and funding situation.
How often should I update the plan?
Update it when important assumptions or decisions change. Major shifts in costs, pricing, staffing, demand, funding, or strategy are good triggers. A quarterly review can keep the plan useful without creating unnecessary work.